

The SumUp Business Account is a UK business money account for sole traders, freelancers and small businesses. It has no monthly fee and includes UK transfers, a business Mastercard, expense tools, invoicing and next-day access to eligible SumUp card-payment takings.
What Is a SumUp Business Account?
A SumUp Business Account gives a business an account number and sort code for managing money in pounds sterling. Account holders can send and receive transfers involving UK GBP accounts and use the included prepaid Mastercard for purchases online or in shops.
It sits within SumUp’s wider payments platform. This means a business can accept customer payments, receive its SumUp payouts, pay expenses, send invoices and review transactions without necessarily moving money between several separate services.
The standard account costs £0 per month. SumUp also offers Business Account Plus for £15 per month, which adds features aimed at businesses with employees or more complicated money-management requirements.
| Feature | Standard Business Account | Business Account Plus |
| Monthly price | £0 | £15 |
| UK business account | Included | Included |
| Business Mastercard | Included | Included |
| UK transfers | Included | Included |
| Free ATM withdrawals | 3 per month | 5 per month |
| Extra balances | No | Up to 3 |
| Additional team cards | No | Up to 3 |
| Cash-deposit fee | 2.5% | 2% |
| Priority support | Standard support | 24/7 priority support |
| Bulk transfers | Standard functionality varies | Up to 500 payments in one bulk transfer |
Prices and features are based on SumUp’s UK information available in September 2026 and can change.
How the SumUp Business Account Works
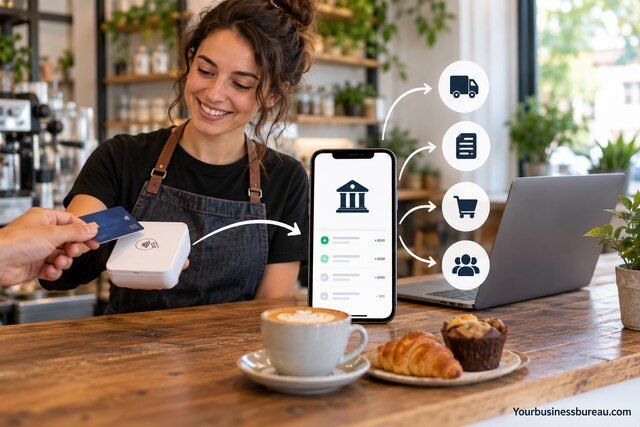
After opening the account and completing verification, you receive account details that can be used to add money and manage business transactions. SumUp says an account can often be set up in less than 10 minutes, although additional verification can make the process longer.
Money can be added by bank transfer or standing order. The account can then be used for outgoing transfers, Direct Debits, card spending and other supported transactions.
The setup becomes particularly useful when the business also accepts payments through SumUp. Instead of sending card takings to an external bank account, SumUp can pay eligible sales into the Business Account the following day. SumUp says this applies even on weekends and bank holidays. Payouts to other accounts generally take one to three business days.
For example, a café that takes £1,200 in SumUp card payments on Saturday can have the eligible payout sent directly to its SumUp Business Account the following day rather than waiting for the normal external-account payout cycle. The business can then use the available balance for suppliers or other expenses.
SumUp Business Account Fees
The standard SumUp Business Account does not have a monthly subscription fee. SumUp also states that transfers and payments using the account do not carry fixed fees.
That does not mean every possible use of the account is free. Cash deposits and ATM usage beyond the included allowance can generate charges.
| Activity | Standard account cost |
| Monthly account fee | £0 |
| UK transfers | £0 |
| Included Mastercard | £0 |
| First 3 ATM withdrawals per month | £0 from SumUp |
| Additional ATM withdrawals | 2% |
| Cash deposits | 2.5% of deposit |
| Business Account Plus | £15 per month |
A third-party ATM operator may impose its own fee even when a withdrawal falls within SumUp’s free allowance. Non-domestic withdrawals are also subject to SumUp’s 2% fee.
Businesses that regularly handle cash should pay particular attention to the deposit charge. Depositing £2,000 in cash during a month at the standard 2.5% rate would cost £50. The 2% Plus rate would reduce the same cost to £40, but the £15 monthly Plus subscription means the cash-deposit saving alone would not cover the subscription in this example.
At £3,000 of monthly cash deposits, the difference between 2.5% and 2% is £15, equal to the current monthly price of Business Account Plus. Other Plus features may affect the calculation as well.
Receiving SumUp Card Payments Into the Account
Fast access to card takings is one of the clearest reasons to combine the Business Account with SumUp’s payment products.
SumUp states that payments taken through its card readers or supported payment solutions can be paid into the Business Account the next day, including weekends and public holidays. Its current UK pricing information says funds can be accessible by 7am the following day.
This can matter for businesses with short cash-flow cycles. A market trader buying stock daily, for example, may value access to weekend takings before the next conventional banking day.
The Business Account itself should not be confused with the fees charged for accepting card payments. SumUp’s payment-processing charges are separate from the £0 monthly price of the standard Business Account. Businesses should therefore calculate the combined cost of their payment-processing plan and any account activities that carry additional fees.
Using the SumUp Business Mastercard
The account includes a SumUp Business Mastercard that can be used for business purchases. SumUp describes it as a prepaid Mastercard rather than a conventional business credit card.
The standard plan currently includes three free ATM withdrawals each month, while Business Account Plus increases the allowance to five. Withdrawals above the allowance are charged at 2%, and an ATM provider can impose additional charges independently.
The card is therefore useful for routine business spending, but companies that withdraw cash frequently should calculate the potential ATM costs before relying on it heavily.
Can You Deposit Cash Into a SumUp Business Account?
Yes. SumUp supports cash deposits through participating retailers. The user generates a deposit barcode in the SumUp app, presents it at a participating retailer and hands over the cash. SumUp says the balance should normally be credited within 10 minutes.
Current cash-deposit limits are:
- Minimum deposit: £20
- Maximum per deposit: £500
- Monthly maximum: £12,000
- Annual maximum: £52,000
The standard cash-deposit fee is 2.5%, while Business Account Plus reduces it to 2%.
These charges make the feature convenient rather than necessarily inexpensive. A cash-heavy retailer depositing £10,000 per month would pay £250 at the standard 2.5% rate before considering other costs. A business receiving almost all revenue electronically would avoid this particular expense.
SumUp Business Account Transaction Limits
SumUp applies transaction limits to transfers, card spending and cash withdrawals.
According to its current UK Business Account information, the default published limits include card payments of up to £15,000 per transaction and per day. Cash withdrawals are limited to £500 per withdrawal and £2,000 per day.
Outgoing transfers have published limits of £25,000 per transfer, £50,000 per day and £150,000 per month. SumUp says there is no equivalent limit on incoming transfers. Customers can request changes to certain limits, although not every requested change is necessarily available.
These limits are unlikely to affect many microbusinesses, but a company regularly making large supplier, payroll or inventory payments should check them before using SumUp as its primary account.
Is the SumUp Business Account Safe?
The SumUp Business Account is regulated differently from an account provided by a licensed UK bank.
SumUp states that it is an electronic money institution authorised by the Financial Conduct Authority, with UK licence number 900700. Customer money is held using safeguarding arrangements rather than being treated like ordinary deposits at a bank.
The FCA explains that authorised electronic money and payment institutions subject to safeguarding rules must protect relevant customer funds, such as by segregating them from other funds or using qualifying insurance or guarantees. The purpose is to protect customers’ relevant money if the institution becomes insolvent.
Safeguarding is not the same as FSCS protection
This distinction deserves attention.
SumUp explicitly states that funds in its Business Account are safeguarded but are not FSCS-protected. In other words, customers should not assume that holding money with SumUp provides the same deposit-protection arrangement as holding eligible deposits with a UK bank covered by the FSCS.
SumUp also uses security features including 3D Secure for online card transactions and biometric verification through supported devices.
For a business deciding where to keep substantial cash reserves, the difference between e-money safeguarding and bank-deposit protection should form part of the decision rather than comparing accounts solely on fees.
Who Can Open a SumUp Business Account?
SumUp markets the account to UK businesses including sole traders, freelancers, start-ups and small businesses. Applicants need to provide business details and complete identity verification before the account is activated.
One less obvious limitation is the account name. SumUp’s support documentation states that a Business Account can only be opened in the name of the signatory associated with the SumUp profile.
A business can generally have a maximum of one Business Account associated with each business profile. Someone operating multiple businesses can have separate accounts where each business has its own SumUp profile and unique email address.
Do Sole Traders and Limited Companies Need a Business Account?
Sole traders are not generally legally required to maintain a separate business bank account in the UK. Separating personal and business transactions can nevertheless make bookkeeping, expense tracking and tax preparation considerably easier. Business.gov.uk confirms that sole traders and ordinary partnerships are not legally required to have business bank accounts.
A limited company’s finances must be kept separate from those of its owners and directors because the company is a separate legal entity. UK government guidance states that company banking must therefore be separate from personal banking and identifies a business bank account as the simplest way to achieve that separation.
Business owners should also check the terms of any personal account before using it for commercial transactions, even where a separate business account is not legally mandatory.
Expense Tracking, Invoicing and Tax Administration
The Business Account goes beyond receiving and spending money. SumUp provides expense-management tools that categorise transactions, allow receipt storage and support transaction exports in formats such as CSV for bookkeeping or accountant use.
Invoicing is also integrated into the SumUp ecosystem, which can be useful for a small business that accepts both card payments and invoice payments.
SumUp has also introduced tools aimed at Making Tax Digital for Income Tax, developed using embedded accounting technology from Sage. However, businesses should distinguish the availability of MTD-related software from whether they are legally required to use MTD.
For the 2026/27 tax year, HMRC requires MTD for Income Tax for qualifying sole traders and landlords whose qualifying self-employment and property income exceeded £50,000 in 2024/25. The threshold falls to more than £30,000 from April 2027 and more than £20,000 from April 2028, based on the relevant earlier tax year.
Standard SumUp Business Account vs Business Account Plus
The free account covers many of the functions a sole trader or very small business is likely to need. Plus becomes more relevant when a business has employees, makes frequent cash deposits or needs to separate money for different purposes.
Business Account Plus currently costs £15 per month and provides up to three additional Mastercards, three extra balances, five free ATM withdrawals per month, bulk transfers, additional invoicing functionality and priority support.
Separate balances can be particularly practical. A business could, for example, maintain its operating balance while placing money intended for tax and recurring bills into separate balances. That does not alter the business’s tax liability, but it can reduce the risk of accidentally spending money earmarked for future obligations.
The free plan remains the more straightforward option where one person runs the business, rarely withdraws cash and does not need multiple spending cards or balances.
When the SumUp Business Account Makes Sense
The account has the clearest practical fit when a business already uses SumUp to take customer payments. Keeping payment acceptance and money management within the same system reduces the number of steps between making a sale and accessing the proceeds.
It may suit sole traders, mobile service providers, cafés, market traders, freelancers and small retailers that value a £0 monthly account and integrated payment tools.
The decision becomes less straightforward for businesses that handle large volumes of cash. A 2.5% standard cash-deposit fee can become significant as deposits increase. Companies needing overdrafts, lending facilities, extensive branch services or sophisticated international banking should also compare alternatives rather than assuming a payment-focused account will cover every requirement.
SumUp’s support documentation describes Business Account transfers as transfers to and from UK-based GBP accounts, so companies with substantial multi-currency or international transfer requirements should verify whether they need an additional provider.
Key Limitations to Consider Before Opening an Account
The £0 monthly price is attractive, but monthly fees should not be the only comparison point.
First, SumUp is an electronic money institution rather than a bank, so its safeguarding model differs from FSCS deposit protection. Second, businesses dealing heavily in physical cash can incur meaningful deposit charges. Third, transaction limits can matter for larger businesses. Fourth, the account is focused primarily on UK GBP transactions rather than broad multi-currency banking.
A useful way to evaluate the account is to look at how the business actually moves money each month. Estimate card sales, cash deposits, ATM withdrawals, supplier transfers and international transactions. That calculation gives a more realistic picture than comparing headline monthly account fees alone.
How to Open a SumUp Business Account
Opening the account is primarily a digital process. SumUp describes three basic stages: create or sign in to a SumUp profile and provide business details, complete identity verification, then access the account once approval is complete.
SumUp says many applicants can complete setup in less than 10 minutes, with account details available once verification is completed. Verification can take longer where information or identification requires further checks.
After activation, money can be added by bank transfer or standing order. Businesses using SumUp’s payment products can then arrange for their eligible payment takings to be paid into the account.
Conclusion
The SumUp Business Account combines a £0 monthly account with UK transfers, a business Mastercard, expense management, invoicing and fast access to eligible SumUp payment takings. That combination can be particularly practical for small businesses already using SumUp to accept card payments.
The headline price should not be considered in isolation. Cash deposits cost 2.5% on the standard plan, ATM allowances are limited, transaction limits apply, and SumUp is an electronic money institution rather than a bank. Its safeguarding arrangements therefore differ from FSCS deposit protection.
Before opening the account, compare those limitations with the way your business actually receives and spends money. For a card-focused small business, the integration and next-day payouts may be the most valuable features. For a cash-heavy, internationally focused or more complex company, comparing SumUp with other business-account options can reveal whether it works better as the primary account or as part of a broader banking setup.
FAQ’s
The standard account has no monthly subscription fee, and SumUp currently charges no fixed fee for supported UK transfers or ordinary account payments. Charges can still apply to services such as cash deposits and ATM withdrawals beyond the included allowance.
No. SumUp states that it is an FCA-authorised electronic money institution in the UK, not a bank. Its Business Account provides account details and payment functionality, but customer funds are protected through safeguarding rather than FSCS deposit protection.
SumUp says eligible card-reader and payment-solution takings can reach the Business Account the following day, including weekends and bank holidays. Its UK pricing page currently states that money can be accessible by 7am the next day.
Yes. Cash can be deposited through participating retailers using a barcode generated in the SumUp app. The standard fee is currently 2.5%, reduced to 2% with Business Account Plus. Deposits are subject to minimum, per-transaction, monthly and annual limits.
Yes. SumUp specifically offers the account to sole traders and freelancers as well as other eligible businesses. Sole traders are not generally legally required to have a separate business bank account, although keeping business and personal transactions separate can simplify accounting.
SumUp says the Business Account can be used for receiving payouts, transfers, card spending and expense management. Whether it can replace every other account depends on the business. Companies needing FSCS-covered deposits, extensive cash handling, borrowing facilities, branch services or broader international and multi-currency functionality may need to compare or retain another account alongside it.
